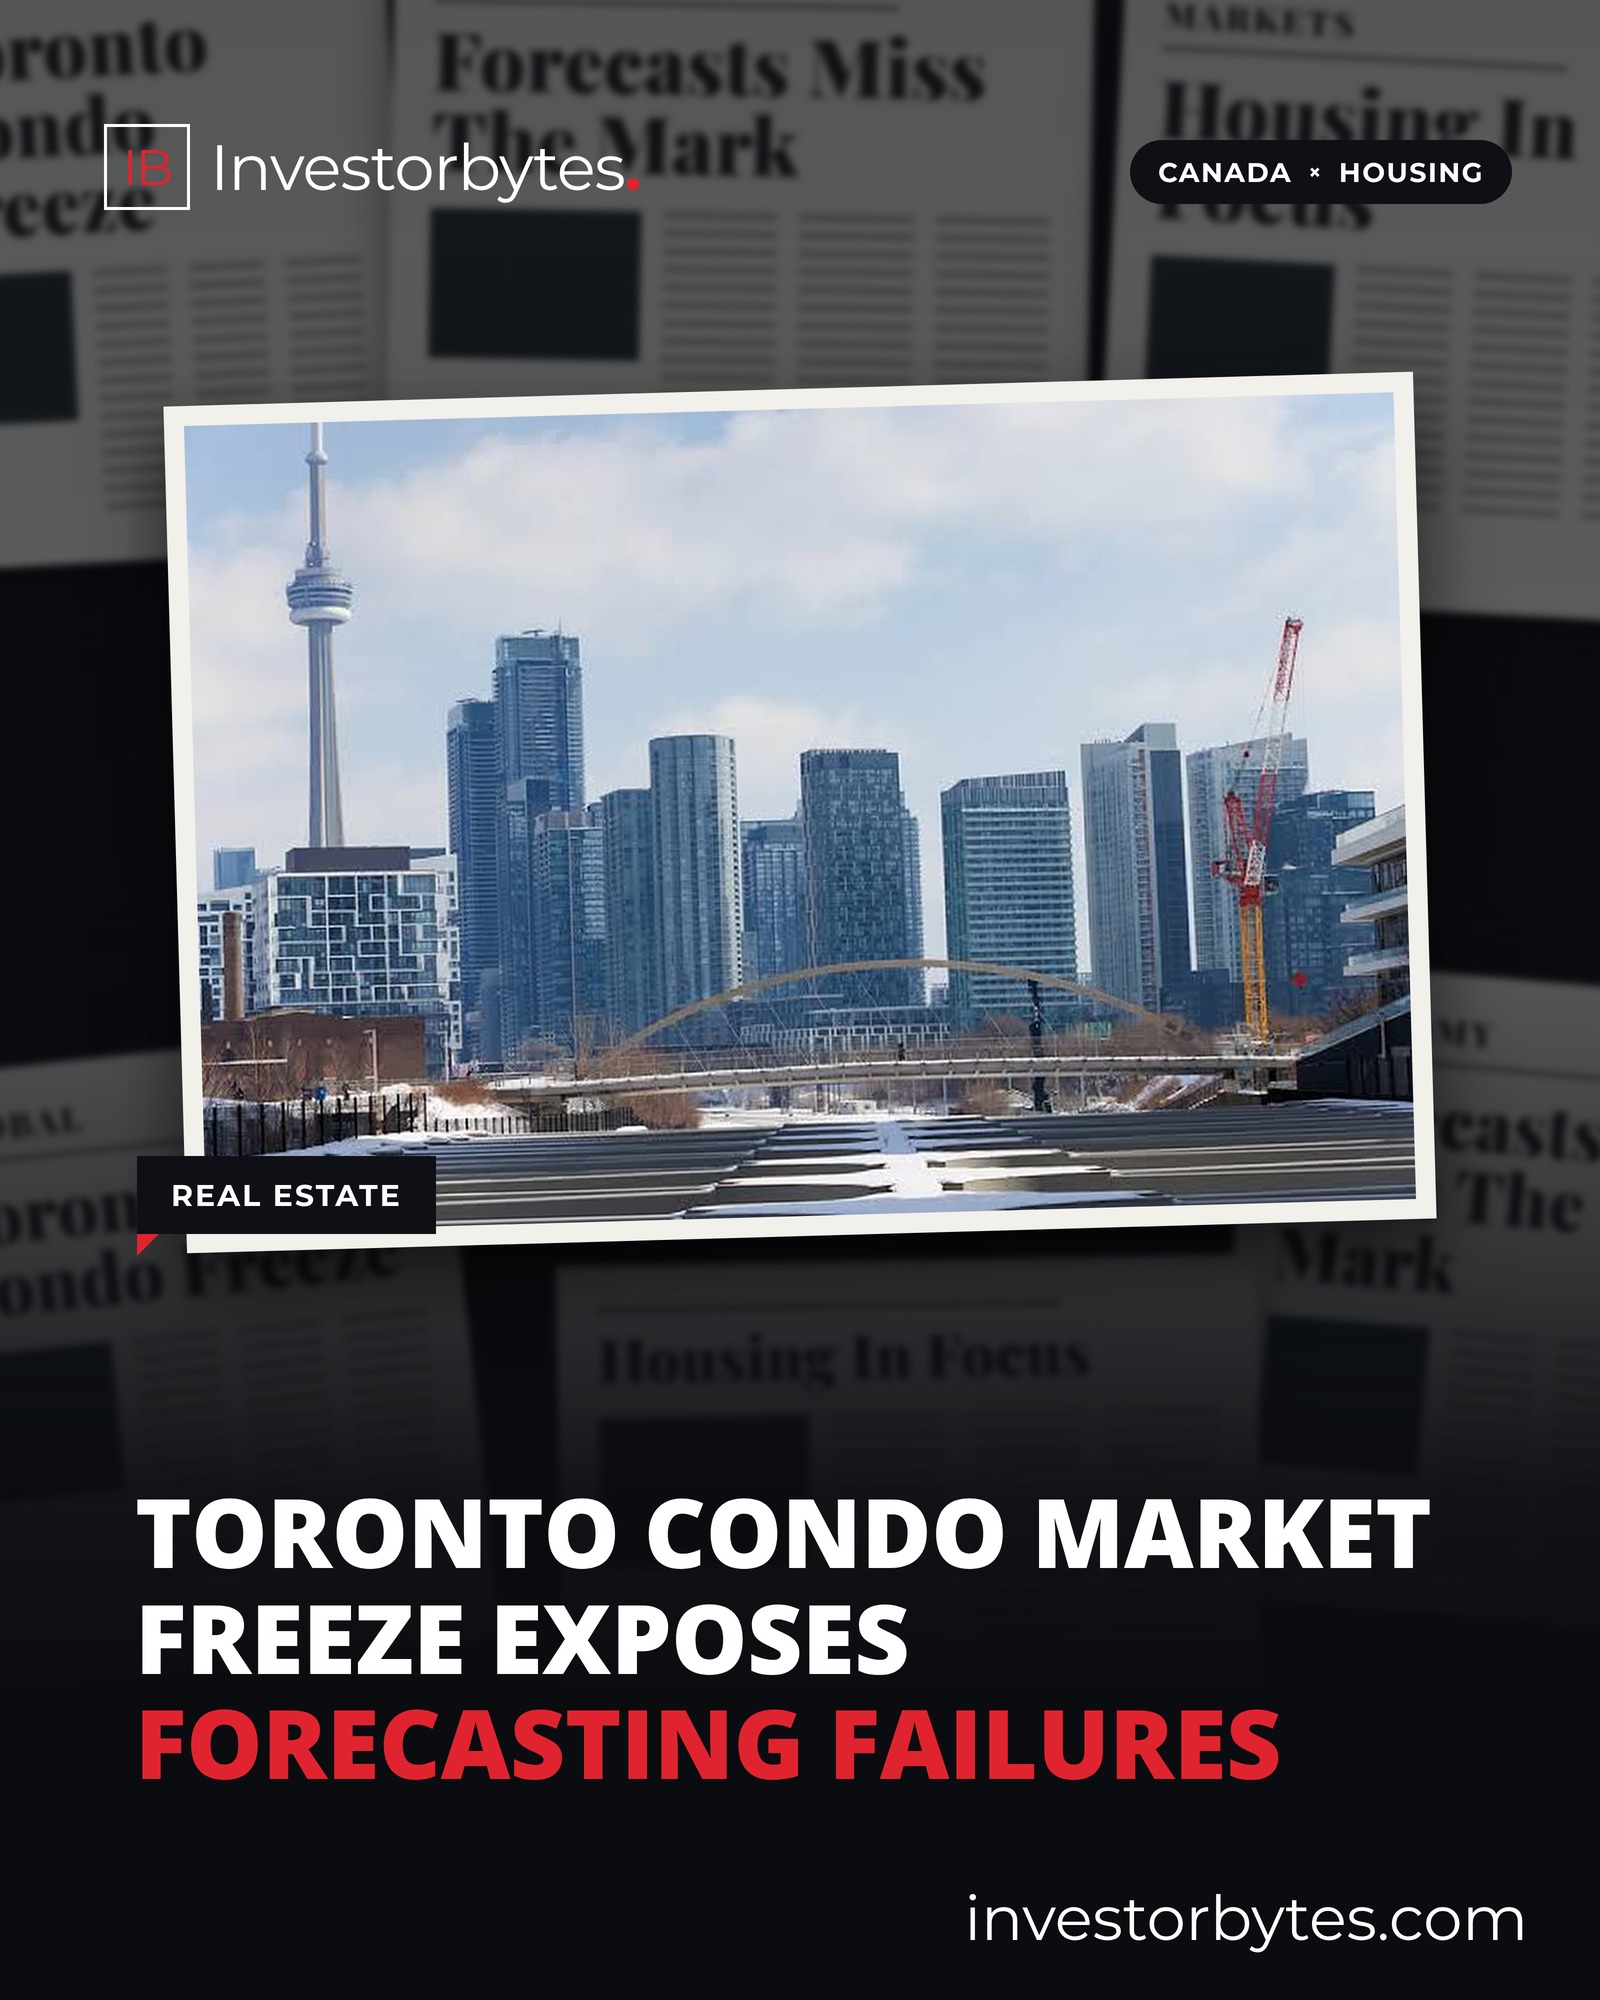
For more than a decade, cranes were the defining feature of Toronto’s skyline. The city became the busiest construction hub in North America, powered by a seemingly endless appetite for new apartments. Today the Toronto condo market tells a very different story. Pre-construction sales have collapsed to record lows, new project launches have all but disappeared, and developers are sitting on an unprecedented stockpile of unsold units.
In a column by economist David Orrell in World Finance, the author argues that the crisis is not only about property. It is also a reminder of how poorly mainstream economic models handle booms, busts and sudden breakdowns, and why forecasters need to take uncertainty far more seriously.
How Toronto Became a Construction Boomtown
Canada came through the 2008 global financial crisis in better shape than most advanced economies. Its banks were more conservatively run and had largely avoided the complex mortgage derivatives that brought down lenders in the United States. That resilience reinforced a widely held belief among Canadians that property was a safe place to put money.
House prices dipped briefly after the crisis, then roughly doubled over the following 12 years and came close to tripling by the time they peaked in 2022. The conventional explanation was strong demand from a rapidly growing population. Canada’s population expanded at around 3.2 percent in 2022, driven almost entirely by immigration, far above the average of roughly 0.5 percent across G7 nations.
Yet the number of existing homes changing hands was relatively stable through much of this period. Orrell’s point is that a large share of the action took place in a different corner of the market: condominiums sold before they had been built.
The Shoebox Bet at the Heart of the Toronto Condo Market
Many of these pre-construction units were small apartments, often nicknamed shoeboxes, bought primarily as investments rather than as homes. The model was simple. An investor put down a relatively modest deposit when a project launched, then hoped to sell the contract at a profit to an end user or another investor before the building was completed. In effect, it worked like a futures contract on the property market, with considerable leverage built in.
As long as prices rose, the model worked. Developers used early sales to secure construction financing, investors booked paper gains, and the pipeline of new towers kept growing. Mainstream economists saw little cause for alarm because the broader economy appeared healthy. Interest rates were cut sharply during the pandemic, and inflation measures used by the central bank did not directly capture house prices, so soaring property values did not trigger a policy response.
When the Music Stopped
The conditions that sustained the boom reversed quickly. Post-pandemic inflation forced the Bank of Canada, like other central banks, to raise interest rates, making mortgages much more expensive. At the same time, the federal government moved to curb immigration, and in 2025 Canada recorded a small population decline, the first on record.
The wider housing market adjusted in the usual way, with sales volumes and prices falling. The pre-construction condo segment, however, did not simply slow down. It stopped. In December 2025 only 87 new condo units were sold across the Greater Toronto Area, a region of around 7.8 million people, the lowest monthly figure in the 45 years such data has been collected. Only ten new condo projects launched during the whole of 2025, compared with the dozens typical in a healthy year, and none at all launched in the first quarter of 2026. Unsold new-home inventory climbed to a record equal to more than two years of sales.
For investors who bought off-plan at peak prices, the consequences can be severe. Units may be worth less on completion than the agreed purchase price, and buyers must still secure mortgages to close at today’s higher borrowing costs. For developers, a lack of pre-sales makes it difficult to obtain financing for new projects, which explains why launches have dried up.
A Lesson in the Limits of Economic Models
Orrell, who writes regularly on the shortcomings of mainstream economics, links the Toronto situation to a broader failure exposed by the financial crisis. Many traditional models assumed that market risks followed a normal distribution, the familiar bell curve, which makes extreme events appear extremely unlikely. In reality, financial markets regularly produce shocks far larger than such models suggest.
Underlying those models was a view of the economy as rational, efficient and self-correcting, a system that naturally gravitates towards equilibrium. Booms and busts were treated as external disturbances rather than features generated by the system itself. The 2008 crisis badly damaged that view, and economists Frank Fabozzi and Sergio Focardi argue in their book Adaptive Finance: Embracing Uncertainty and Complexity that conventional approaches failed to anticipate events such as the collapse of major institutions and the sudden freezing of credit markets.
The Toronto episode follows a similar pattern. A market built on leverage, expectations and continuous resale can appear stable for years, then seize up abruptly when one or two key assumptions change. Linear forecasts based on past trends are poorly suited to spotting that kind of tipping point.
What Comes Next for Toronto and Beyond
A recovery in the Toronto condo market is likely to require a combination of lower borrowing costs, renewed population growth and a reset in pricing that brings new units back within reach of people who actually want to live in them. Some observers argue that the freeze could eventually shift construction towards purpose-built rental housing and larger family-sized units, which have long been in short supply.
The lesson extends well beyond Canada. Investor-driven pre-sale markets exist in many fast-growing cities, and policymakers everywhere rely on models that may underestimate the risk of sudden breakdowns.
Conclusion
Toronto’s condo freeze is both a property story and an intellectual one. It shows how a market built on speculative pre-sales can switch off almost overnight, and how forecasting tools that assume stability can miss the warning signs. As Orrell suggests, the deterministic models of the past are giving way to approaches that treat uncertainty as central. With another market in deep freeze, economists and policymakers have every reason to adopt them.